Categories
Mortgage MinutePublished November 16, 2026
Mortgage Rates Are Up. Here's Why Buyers May Have More Room to Negotiate
Mortgage Rates Are Up. Here's Why Buyers May Have More Room to Negotiate
There's a home you've had your eye on for a while. You like the neighborhood, the layout works, and you can picture yourself living there. But every time you look at the mortgage payment, you hesitate.
Then you notice something interesting. The asking price has changed.
Maybe the seller reduced it last week. Maybe the home has been available longer than expected. And while mortgage rates haven't exactly been cooperating, the circumstances surrounding that particular property may be starting to look different.
It's a situation worth paying attention to as we move toward the end of the year.
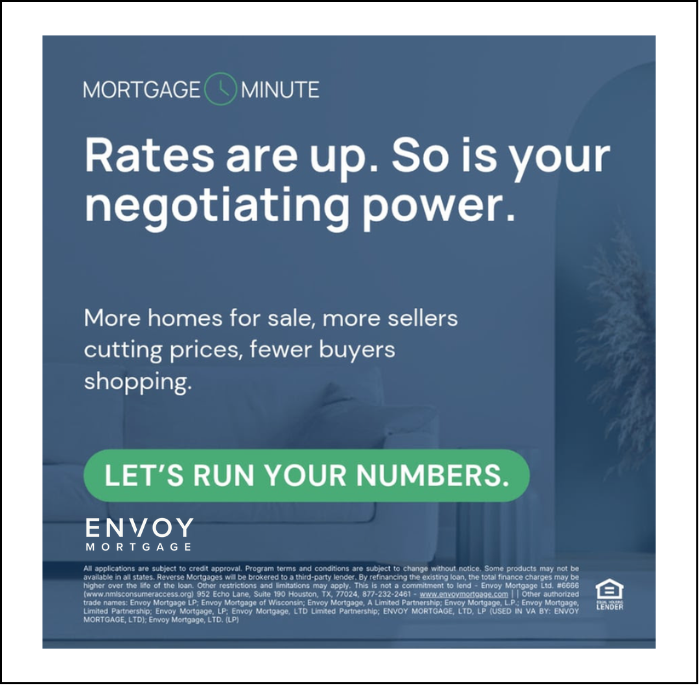
According to this week's Mortgage Minute from Envoy Mortgage, the average 30-year fixed mortgage rate climbed to approximately 7.5% last week following a hotter inflation report. That's not welcome news for buyers hoping borrowing costs would continue improving.
But higher mortgage rates can also change how people behave in the housing market. Some buyers postpone their search, while others become more selective about which homes they'll consider. Sellers who want to move forward may find themselves having to work a little harder to attract an offer.
For buyers who can comfortably afford today's payments, that change can create opportunities.
The question isn't whether mortgage rates are high. It's whether the home, the price, and the terms of the purchase make sense for you.
Higher Rates Change More Than Your Mortgage Payment
When mortgage rates increase, the first thing most buyers notice is the monthly payment.
A home that seemed manageable a few weeks earlier may suddenly feel more expensive. Even buyers who have been preapproved can find themselves reconsidering their price range or delaying their plans.
And that's understandable. A mortgage is a long-term commitment, and the payment needs to fit comfortably within your budget.
But there's another side to what happens when rates rise.
Some buyers step away from the market. Others continue searching but become more cautious about making offers. Properties that might have attracted considerable interest during a busier period can sometimes remain available longer.
That doesn't mean every home becomes easier to buy. A well-priced property in a desirable location may still attract strong competition, regardless of the broader mortgage environment.
It does mean that the experience of shopping for a home can change.
You may have more time to compare properties, revisit a listing, or discuss terms with a seller who hasn't received the response they expected.
For someone who has already worked through their financing and knows what they can afford, those circumstances can be valuable.
More Homes, More Choices, and a Different Conversation
One of the more interesting details in this week's Envoy Mortgage update is the change in available inventory.
According to the supplied national market figures, there are approximately 7% more homes for sale than at the same time last year. More than four in ten active listings have also experienced a price reduction.
Those figures don't describe every neighborhood in Northern California, but they offer some context for what's happening in the broader housing market.
Sellers are responding to buyer activity, and some are reconsidering their original asking prices.
Imagine two similar homes in the same neighborhood. One just came on the market and has attracted several showings. The other has been listed for six weeks, and the seller recently reduced the price.
Both properties might be worth considering, but the conversations surrounding them could be very different.
With the newer listing, the seller may want to see how much interest develops before discussing concessions. With the longer-listed property, there may be more willingness to consider an offer that addresses the buyer's financial priorities.
Of course, a price reduction doesn't guarantee that a seller will accept another discount.
Sometimes a property was simply priced too high to begin with. Other times, the home needs repairs or improvements that buyers are factoring into their offers.
That's why the listing history matters.
At EO&A, we can look at how long a property has been available, whether its price has changed, and how it compares with other homes in the area. Those details help us determine whether there may be a realistic opportunity to negotiate.
The Best Negotiation Isn't Always About Price
A lower purchase price is appealing for obvious reasons. You pay less for the home, and depending on your financing, you may need to borrow less.
But when mortgage rates are elevated, buyers often care just as much about what they'll pay each month.
That makes seller credits worth discussing.
Depending on the loan program and the terms of the purchase, a seller may be able to contribute toward eligible closing costs or certain financing expenses.
For a buyer who wants to preserve savings after moving, an allowable closing-cost credit may be particularly useful.
Another buyer might prefer to explore a mortgage rate buydown that could reduce their payment. Some buydowns provide temporary payment relief, while other financing arrangements may involve discount points that reduce the rate for the life of the loan.
The available options and their costs depend on the lender and loan program.
A seller contribution isn't automatically better than a lower purchase price, and buyers shouldn't assume every seller will agree to provide one.
What matters is understanding the difference before deciding what to request.
If you've found a home you like, your lender can compare the numbers for a lower purchase price and an eligible seller credit. Your agent can evaluate whether either request is realistic given the property's circumstances.
That gives you a much clearer picture than simply asking for the largest possible discount.
And when the monthly payment is already close to the top of your comfort range, having that information becomes especially important.
Winter Has Its Own Real Estate Rhythm
There's a reason some buyers enjoy looking for homes during the quieter months.
Holiday schedules fill up, families make travel plans, and moving becomes less of a priority for people who aren't working toward a particular deadline.
As a result, fewer buyers may be actively touring homes.
For someone who's still searching, that can mean less competition for certain properties.
This week's Envoy Mortgage update also highlights an interesting seasonal pattern in national home prices. Looking at selected years between 2018 and 2025, the supplied figures show that the national median existing-home price rose approximately 10% to 17% between January and June, then declined approximately 7% to 13% by the following January.
That doesn't mean individual homes lose that amount of value every winter. National median prices can change partly because the mix of homes being sold changes throughout the year.
It also doesn't mean buyers should expect the same pattern to repeat this winter.
What it does illustrate is that seasonality can affect the market, and the quieter months may offer a different negotiating environment than spring.
There is a trade-off, though.
The number of homes available for sale often decreases as the holidays approach. Buyers who wait until January may encounter less competition, but they may also have fewer properties to choose from.
If you're already considering a move, there's value in looking at what's available now rather than assuming a better selection or lower price will automatically appear later.
Northern California Is a Collection of Different Markets
A national housing statistic can help explain a broader trend, but it can't tell you exactly what's happening with a particular home in Napa, Santa Rosa, Fairfield, San Rafael, Walnut Creek, or Oakland.
Each community has its own inventory, price ranges, and buyer activity.
Even within the same city, two homes can experience very different levels of interest.
A property that's move-in ready and priced competitively may attract buyers quickly. Another home that needs substantial updates or has been priced above comparable properties may remain available longer.
That's why we don't approach every listing with the same negotiating strategy.
For buyers searching throughout Northern California, the most useful information is often specific to the property they're considering.
We want to understand the asking price in relation to comparable homes, whether the property has already been reduced, how long it's been available, and what other options buyers have nearby.
Those details help us decide whether to recommend a straightforward offer, a price adjustment, an allowable seller credit, or another term that could benefit the buyer.
Higher mortgage rates may create more negotiating opportunities in certain situations, but they don't replace the need to evaluate each home carefully.
Buying a Rental Property Before Year-End
For buyers considering an investment property, the final weeks of the year can bring an additional consideration: taxes.
This week's Envoy Mortgage update notes that year-end timing may matter for rental property purchases, particularly when an investor hopes to claim eligible deductions associated with the property during the current tax year.
Generally, purchasing a rental property isn't the only step that matters. Whether the property has been placed in service, meaning it's ready and available for its intended rental use, can affect when certain tax deductions begin.
That distinction is important for anyone hoping to complete a purchase before December 31.
Closing on a property and placing it in service aren't necessarily the same event, and tax treatment depends on the investor's circumstances.
If you're considering purchasing a rental property before the end of 2026, speak with your tax professional about the applicable requirements before making decisions based on a potential deduction.
EO&A can help with the real estate side of the purchase, including evaluating available properties and coordinating transaction timelines, while your tax advisor and lender can address the financial considerations.
Being Prepared Matters More Than Predicting Rates
One of the hardest parts of buying a home is deciding when to move forward.
Mortgage rates change. New homes come on the market. Sellers adjust prices, and the level of competition can look different from one month to the next.
It's tempting to wait until everything lines up perfectly.
But there isn't a way to know exactly when mortgage rates will fall, when a particular home will be reduced, or whether the same property will still be available a few months from now.
What you can do is prepare.
Start by asking your lender to calculate your estimated monthly payment using current financing options. Make sure you're considering the full cost of ownership, including property taxes, insurance, and any applicable homeowners association fees.
Think about how much cash you want to have available after closing and whether you're comfortable with the payment over the long term.
Then look at the homes that fit those numbers.
You may find a property that's been on the market longer than expected. Perhaps the seller has already reduced the price or is willing to discuss an eligible closing-cost credit.
Or you may discover that the available homes still don't meet your needs or budget.
Either outcome gives you useful information.
The goal isn't to buy simply because competition has slowed. It's to be prepared when a home and its terms make financial sense.
A Good Opportunity Starts With the Right Numbers
Mortgage rates moved higher last week, and there's no guarantee where they'll go next.
But higher rates don't tell the entire story of today's housing market.
With more national inventory than a year ago, price reductions on many listings, and fewer buyers shopping as the holidays approach, some sellers may be more willing to negotiate.
For buyers who are financially prepared, that creates a reason to keep paying attention.
If you're considering buying a home in Napa, Sonoma, Solano, Marin, Contra Costa, Alameda, San Francisco, or the surrounding Northern California communities, EO&A can help you explore available properties and identify situations where negotiations may be worth pursuing.
We'll look at the property, the listing history, and the local competition. Your lender can help determine what today's mortgage rates and potential seller credits would mean for your monthly payment.
You don't need to predict the next interest rate announcement to make a thoughtful decision.
You need to understand your numbers, recognize the right opportunity, and purchase a home with terms you're comfortable with.
Happy house hunting 🏡
Source: Weekly Mortgage Minute information and graphic provided by Envoy Mortgage. The supplied update attributes rate information to Mortgage News Daily, inventory and price-reduction figures to Altos Research via HousingWire, and historical seasonal pricing figures to the National Association of Realtors. These figures have not been independently verified for this article and are national, not local, statistics. Mortgage terms, seller concessions, and investment-property tax considerations depend on individual circumstances. Consult a qualified lender and tax professional for personalized guidance.
Frequently Asked Questions About Mortgage Rates and Buyer Negotiating Power
Do higher mortgage rates give buyers more negotiating power?
Higher mortgage rates can sometimes create more negotiating opportunities because some buyers pause their searches or reduce their budgets. With fewer competing buyers, certain homes may remain on the market longer, and sellers may become more open to discussing price or other terms. However, this varies by property and location. A well-priced home can still attract multiple offers, even when mortgage rates are elevated.
Can I ask a seller to pay some of my closing costs?
Yes. Buyers can request that a seller contribute toward eligible closing costs as part of a purchase offer. Whether the seller agrees depends on the property's circumstances and the negotiation. The amount and permitted uses of seller credits also depend on the buyer's financing program. Your lender can explain the applicable limits, while your real estate agent can help determine whether requesting a credit makes sense.
Is winter a good time to buy a home in Northern California?
Winter can offer opportunities for buyers because fewer people may be actively shopping during the holiday season. Some sellers may be more willing to negotiate, particularly when their properties have been available for an extended period. However, the selection of homes often decreases during the colder months. Buyers should consider their finances, available inventory, and local conditions rather than assuming winter always brings lower prices.
Should I wait for mortgage rates to drop before buying a home?
Waiting may be appropriate if today's mortgage payment would put too much pressure on your budget. However, future rate movements are uncertain, and lower rates don't guarantee that a particular home will become more affordable. Buyers who can comfortably afford current payments may find negotiating opportunities on certain properties. Reviewing updated financing estimates and available homes can help you decide whether to purchase or continue waiting.
What should I look for when negotiating on a home that has reduced its price?
Start by reviewing how long the property has been listed, when the asking price changed, and how it compares with similar homes. A price reduction may indicate that the seller is responding to buyer activity, but it doesn't guarantee additional flexibility. Your agent can help evaluate the property and determine whether a lower offer, eligible seller credit, or another contract term would be reasonable.
Does buying a rental property before December 31 provide tax benefits?
Purchasing a rental property before December 31 may affect certain tax considerations, but closing before year-end does not automatically qualify an investor for deductions. The property's placed-in-service date and other tax requirements can matter. Investors should speak with a qualified tax professional about depreciation, deductible expenses, and applicable rules before making a purchase based on expected tax benefits.
Search Homes • Buyer Services • Meet the EO&A Team
Contact EO&A today to schedule your free home value review.
Your Trusted Real Estate Advisors across Northern California
Whether you’re planning to sell in San Francisco, Marin, Napa, Sonoma, Solano, Yolo, Sacramento, Contra Costa, or Alameda County, our team has local experts ready to help you navigate your next move with confidence and strategy.
EO&A Team
Elizabeth, Anne, Ian, Ksenia, Cliff, Annie, Mike, Nina, Sidra, Karen, Annie, Steven, Gladys, Venus, Najat, Courtney, David, and Juan
707.312.0819 • hello@eoanda.com • www.eoanda.com
DRE# 01388551 • GUIDE Real Estate DRE# 01976964
Information is provided for general educational purposes. Property availability, pricing, and open-house schedules can change. Confirm current details with a licensed real estate professional.
Anne Kennedy
Broker Associate | EO&A | Real Estate in Napa, Sonoma, Solano, Marin, and San Francisco
or another way